ข้อมูล option และ Greeks (Bybit)
tutorial นี้ใช้ Rust เท่านั้น โดยใช้ LiveNode ของ Rust
ร่วมกับ adapter ของ Bybit เพื่อ stream option Greeks แบบ live และ snapshot ของ chain
ที่รวมไว้แล้ว
tutorial นี้เชื่อมต่อกับตลาด option แบบ live ของ Bybit และรับข้อมูล Greeks
และ option chain ผ่านตัวอย่าง DataActor สองตัว ครอบคลุมการค้นหา
instrument, การ subscribe Greeks ที่ venue ให้มา และ snapshot ของ chain
เป็นระยะพร้อมการกรอง strike แบบอิงกับ ATM
บทนำ
Bybit publish Greeks (delta, gamma, vega, theta) และ implied volatility มาพร้อมกับการอัปเดต option ticker ทุกครั้ง NautilusTrader เปิดให้ใช้ข้อมูลนี้ใน สองระดับ:
- Greeks ราย instrument: subscribe สัญญา option เดียวแล้ว
รับ event
OptionGreeksทุกครั้งที่ ticker อัปเดต - Snapshot ของ option chain: subscribe ทั้งชุดวันหมดอายุ (expiry series) แล้ว
รับ event
OptionChainSliceเป็นระยะ ซึ่งรวม quote และ Greeks ของทุก strike ที่ active ไว้
binary ตัวอย่างสองตัวแสดงรูปแบบเหล่านี้ ตัวแรก subscribe stream ของ Greeks ทีละตัว ตัวที่สอง subscribe chain ที่รวมไว้แล้วพร้อมการกรอง strike แบบอิงกับ ATM
flowchart LR
    subgraph BybitAPI ["Bybit V5 public WebSocket"]
        TKR["Per-contract option ticker"]
    end

    subgraph Adapter ["nautilus-bybit data client"]
        Q["QuoteTick + OptionGreeks per contract"]
        AGG["Per-series aggregator<br/>(ATM and strike filtering)"]
    end

    subgraph Actors ["DataActor implementations"]
        G["GreeksTester<br/>on_option_greeks()"]
        C["OptionChainTester<br/>on_option_chain()"]
    end

    TKR --> Q
    Q --> G
    Q --> AGG
    AGG -->|interval timer| C
สิ่งที่ต้องมีก่อน
- Rust toolchain ที่ใช้งานได้ (rustup.rs)
- repository ของ NautilusTrader ที่ clone มาแล้วและ build ได้
ตัวอย่างไม่ต้องใช้ API key ของ Bybit โดยปล่อย api_key และ api_secret ไว้โดยไม่ตั้งค่า data client จึงใช้
endpoint market data สาธารณะของ Bybit และไม่อ่าน credential จาก environment
demo trading ของ Bybit ใช้ stream-demo.bybit.com สำหรับ private stream เท่านั้น
market data ของ option แบบสาธารณะใช้ public stream ของ mainnet
wss://stream.bybit.com/v5/public/option
รูปแบบของ DataActor
DataActor ใน Rust ต้องมีสามส่วน:
- struct ที่มีฟิลด์
core: DataActorCoreและสถานะของคุณเอง - macro
nautilus_actor!(YourType)และ implementation ของDebug - implementation ของ trait
DataActorพร้อม callback ของคุณ
macro จะจัดการการเชื่อมต่อกับ runtime แบบ native ที่ implementation แบบ blanket ของ Actor และ Component
ต้องการ คุณ implement เฉพาะ callback ที่ต้องการ เพราะทุก callback มี implementation เริ่มต้นที่ไม่ทำอะไร (no-op)
ส่วนที่ 1: Greeks ราย instrument
ตัวอย่าง bybit-greeks-tester จะ subscribe OptionGreeks ของ
BTC CALL option ทั้งหมดที่วันหมดอายุใกล้ที่สุด และ log ทุกการอัปเดต
โครงสร้างของ actor
#[derive(Debug)]
struct GreeksTester {
    core: DataActorCore,
    client_id: ClientId,
    subscribed_instruments: Vec<InstrumentId>,
}

nautilus_actor!(GreeksTester);

impl GreeksTester {
    fn new(client_id: ClientId) -> Self {
        Self {
            core: DataActorCore::new(DataActorConfig {
                actor_id: Some("GREEKS_TESTER-001".into()),
                ..Default::default()
            }),
            client_id,
            subscribed_instruments: Vec::new(),
        }
    }
}
macro ต้องการฟิลด์ core ส่วน client_id ระบุ data client สำหรับการ subscribe และ vector
subscribed_instruments จะบันทึก subscription ไว้เพื่อให้ actor ลบออกได้ตอน stop
การค้นหา instrument
ตอน start actor จะ query cache เพื่อหา option instrument ทั้งหมด กรองเฉพาะ BTC CALL ที่ยังไม่หมดอายุ แล้วหาวันหมดอายุ ที่ใกล้ที่สุด:
fn on_start(&mut self) -> anyhow::Result<()> {
    let venue = Venue::new("BYBIT");
    let underlying_filter = Ustr::from("BTC");

    let mut options: Vec<(InstrumentId, f64, u64)> = {
        let cache = self.cache();
        let instruments = cache.instruments(&venue, Some(&underlying_filter));

        instruments
            .iter()
            .filter_map(|inst| {
                if inst.option_kind() == Some(OptionKind::Call) {
                    let expiry = inst.expiration_ns()?.as_u64();
                    let strike = inst.strike_price()?.as_f64();
                    Some((inst.id(), strike, expiry))
                } else {
                    None
                }
            })
            .collect()
    }; // cache borrow dropped here

    let now_ns = self.timestamp_ns().as_u64();
    options.retain(|(_, _, exp)| *exp > now_ns);

    let nearest_expiry = options.iter().map(|(_, _, exp)| *exp).min().unwrap();
    options.retain(|(_, _, exp)| *exp == nearest_expiry);
    options.sort_by(|(_, a, _), (_, b, _)| a.partial_cmp(b).unwrap());

    // ...subscribe to each
}
ให้ปล่อยการยืม (borrow) cache ก่อนเรียก method สำหรับ subscribe ใดๆ
cache ใช้ Rc<RefCell<...>> ภายใน และ method สำหรับ subscribe อาจ
ต้องยืมมันด้วย ให้รวบรวมข้อมูลที่เป็นเจ้าของเองไว้ใน Vec ในเครื่อง ทิ้ง reference
ของ cache แล้วจึง subscribe
การ subscribe Greeks
หลังค้นหา instrument แล้ว ให้ subscribe ทีละตัว:
let client_id = self.client_id;
for (instrument_id, _, _) in &options {
    self.subscribe_option_greeks(*instrument_id, Some(client_id), None);
    self.subscribed_instruments.push(*instrument_id);
}
การจัดการการอัปเดต
การอัปเดต ticker แต่ละครั้งจาก Bybit จะ trigger on_option_greeks พร้อม
event OptionGreeks:
fn on_option_greeks(&mut self, greeks: &OptionGreeks) -> anyhow::Result<()> {
    log::info!(
        "GREEKS | {} | delta={:.4} gamma={:.6} vega={:.4} theta={:.4} rho={:.6} | \
         mark_iv={} bid_iv={} ask_iv={} | underlying={} oi={}",
        greeks.instrument_id,
        greeks.delta,
        greeks.gamma,
        greeks.vega,
        greeks.theta,
        greeks.rho,
        greeks.mark_iv.map_or("-".to_string(), |v| format!("{v:.2}")),
        greeks.bid_iv.map_or("-".to_string(), |v| format!("{v:.2}")),
        greeks.ask_iv.map_or("-".to_string(), |v| format!("{v:.2}")),
        greeks.underlying_price.map_or("-".to_string(), |v| format!("{v:.2}")),
        greeks.open_interest.map_or("-".to_string(), |v| format!("{v:.1}")),
    );
    Ok(())
}
ฟิลด์ของ OptionGreeks:
| ฟิลด์ | Type | คำอธิบาย |
|---|---|---|
instrument_id | InstrumentId | สัญญา option |
convention | GreeksConvention | convention ของ Greeks (BlackScholes หรือ PriceAdjusted) |
delta | f64 | ความอ่อนไหวของราคาต่อ underlying |
gamma | f64 | ความอ่อนไหวของ delta ต่อ underlying |
vega | f64 | ความอ่อนไหวของราคาต่อการเปลี่ยนแปลงของ volatility 1% |
theta | f64 | การลดลงของมูลค่าตามเวลารายวัน |
rho | f64 | ความอ่อนไหวต่อการเปลี่ยนแปลงของอัตราดอกเบี้ย |
mark_iv | Option<f64> | implied volatility ของ mark price |
bid_iv | Option<f64> | bid implied volatility |
ask_iv | Option<f64> | ask implied volatility |
underlying_price | Option<f64> | ราคาอ้างอิงของ venue สำหรับวันหมดอายุนี้ |
open_interest | Option<f64> | open interest ของสัญญานี้ |
ts_event | UnixNanos | UNIX timestamp (นาโนวินาที) เมื่อ event เกิดขึ้น |
ts_init | UnixNanos | UNIX timestamp (นาโนวินาที) เมื่อ instance ถูก initialize |
ค่า delta, gamma, vega, theta และ rho อยู่ใน struct ซ้อน greeks: OptionGreekValues
implementation Deref<Target = OptionGreekValues> ของ OptionGreeks ทำให้เข้าถึงได้โดยตรงผ่าน
greeks.delta และฟิลด์อื่นๆ ดังที่แสดงข้างต้น
Bybit ไม่ได้ให้ค่า rho adapter จึงตั้งเป็น 0.0
การเก็บกวาด
ตอน stop ให้ unsubscribe จากทุก instrument:
fn on_stop(&mut self) -> anyhow::Result<()> {
    let ids: Vec<InstrumentId> = self.subscribed_instruments.drain(..).collect();
    let client_id = self.client_id;
    for instrument_id in ids {
        self.unsubscribe_option_greeks(instrument_id, Some(client_id), None);
    }
    log::info!("Unsubscribed from all option greeks");
    Ok(())
}
ส่วนที่ 2: snapshot ของ option chain
ตัวอย่าง bybit-option-chain จะ subscribe option chain ที่รวมไว้แล้ว
และ log snapshot เป็นระยะ โดยแสดง call และ put ที่แต่ละ strike พร้อม
quote และ Greeks ของมัน
ทำไมต้องใช้ option chain
subscription ราย instrument ให้การควบคุมสัญญาแต่ละตัว แต่สำหรับทั้ง surface คุณต้องจัดการ
stream แต่ละตัวและเชื่อมโยงการอัปเดตข้าม strike เอง subscription แบบ option chain ทำสิ่งนี้ให้ผ่าน
DataEngine โดยรวม quote และ Greeks ของทุก strike ในชุดเดียวกัน แล้ว publish
OptionChainSlice เดียวตาม timer
การรวมนี้เกิดขึ้นภายใน NautilusTrader Bybit publish market data ของ option แยกตามสัญญา และเอกสาร public WebSocket ของ V5 ไม่ได้ระบุ stream ของ option chain แบบ native ไว้
Type ที่เกี่ยวกับ chain
OptionSeriesId ระบุชุดวันหมดอายุหนึ่งชุด:
let series_id = OptionSeriesId::new_derived(
    Venue::new("BYBIT"),    // venue
    Ustr::from("BTC"),      // underlying
    Ustr::from("USDT"),     // settlement currency
    UnixNanos::from(expiry), // expiration timestamp
);
StrikeRange ควบคุมว่า strike ใดจะ active:
| Variant | คำอธิบาย |
|---|---|
Fixed | ชุดราคา strike ที่กำหนดตายตัว |
AtmRelative | strikes_above strike เหนือ ATM และ strikes_below strike ใต้ ATM |
AtmPercent | ทุก strike ที่อยู่ภายใน pct ของราคา ATM |
Delta | strike ที่ค่าสัมบูรณ์ของ delta ของ call หรือ put อยู่ภายใน tolerance จาก target |
สำหรับช่วง strike แบบ dynamic subscription จะรอจนกว่า engine จะกำหนดราคา ATM ได้จาก ราคาอ้างอิงที่ venue ให้มา
การ subscribe
let strike_range = StrikeRange::AtmRelative {
    strikes_above: 3,
    strikes_below: 3,
};

let snapshot_interval_ms = Some(5_000); // snapshot every 5 seconds

self.subscribe_option_chain(
    series_id,
    strike_range,
    snapshot_interval_ms,
    Some(client_id),
    None, // params
);
สำหรับโหมด raw ให้ส่ง None เป็น snapshot_interval_ms ในโหมดนี้ การอัปเดต quote หรือ Greeks ทุกครั้งจะ publish
slice ทันที
การจัดการ snapshot
callback on_option_chain จะได้รับ OptionChainSlice ที่มี
strike ที่ active ทั้งหมดพร้อมข้อมูล call และ put:
fn on_option_chain(&mut self, slice: &OptionChainSlice) -> anyhow::Result<()> {
    log::info!(
        "OPTION_CHAIN | {} | atm={} | calls={} puts={} | strikes={}",
        slice.series_id,
        slice.atm_strike.map_or("-".to_string(), |p| format!("{p}")),
        slice.call_count(),
        slice.put_count(),
        slice.strike_count(),
    );

    for strike in slice.strikes() {
        let call_info = slice.get_call(&strike).map(|d| {
            let greeks_str = d.greeks.as_ref().map_or("-".to_string(), |g| {
                format!(
                    "d={:.3} g={:.5} v={:.2} iv={:.1}%",
                    g.delta, g.gamma, g.vega,
                    g.mark_iv.unwrap_or(0.0) * 100.0,
                )
            });
            format!("bid={} ask={} [{}]", d.quote.bid_price, d.quote.ask_price, greeks_str)
        });

        let put_info = slice.get_put(&strike).map(|d| {
            let greeks_str = d.greeks.as_ref().map_or("-".to_string(), |g| {
                format!(
                    "d={:.3} g={:.5} v={:.2} iv={:.1}%",
                    g.delta, g.gamma, g.vega,
                    g.mark_iv.unwrap_or(0.0) * 100.0,
                )
            });
            format!("bid={} ask={} [{}]", d.quote.bid_price, d.quote.ask_price, greeks_str)
        });

        log::info!(
            "  K={} | CALL: {} | PUT: {}",
            strike,
            call_info.unwrap_or_else(|| "-".to_string()),
            put_info.unwrap_or_else(|| "-".to_string()),
        );
    }

    Ok(())
}
ฟิลด์และ method ของ OptionChainSlice:
| ชื่อ | Type / ค่าที่คืน | คำอธิบาย |
|---|---|---|
series_id | OptionSeriesId | ชุดที่ snapshot นี้ครอบคลุม |
atm_strike | Option<Price> | strike ATM จากราคาอ้างอิง |
call_count() | usize | จำนวน strike ของ call ที่มีข้อมูล |
put_count() | usize | จำนวน strike ของ put ที่มีข้อมูล |
strike_count() | usize | ยูเนียนของ strike ทั้งหมด |
strikes() | Vec<Price> | list ของราคา strike ทั้งหมดที่เรียงแล้ว |
get_call(k) | Option<&OptionStrikeData> | quote และ Greeks ของ call ที่ strike k |
get_put(k) | Option<&OptionStrikeData> | quote และ Greeks ของ put ที่ strike k |
OptionStrikeData แต่ละตัวมี quote: QuoteTick (bid/ask) และ
greeks: Option<OptionGreeks> แบบ optional
การตั้งค่า node
ทั้งสองตัวอย่างใช้รูปแบบ LiveNode เดียวกัน และไม่ต้องใช้ execution client
สำหรับการใช้งานเฉพาะข้อมูล:
#[tokio::main]
async fn main() -> Result<(), Box<dyn std::error::Error>> {
    dotenvy::dotenv().ok();

    let environment = Environment::Live;
    let trader_id = TraderId::from("TESTER-001");
    let client_id = ClientId::new("BYBIT");

    let bybit_config = BybitDataClientConfig {
        api_key: None,    // public market data needs no credentials
        api_secret: None,
        product_types: vec![BybitProductType::Option],
        ..Default::default()
    };

    let client_factory = BybitDataClientFactory::new();

    let mut node = LiveNode::builder(trader_id, environment)?
        .with_name("BYBIT-OPTIONS-001".to_string())
        .add_data_client(None, Box::new(client_factory), Box::new(bybit_config))?
        .with_delay_post_stop_secs(5)
        .build()?;

    let actor = GreeksTester::new(client_id); // or OptionChainTester
    node.add_actor(actor)?;
    node.run().await?;

    Ok(())
}
เมื่อตั้ง product_types เป็น [BybitProductType::Option] client จะโหลดเฉพาะ option instrument ตอน startup
จะรอขณะที่ instrument provider ดึงและ parse option ทุกตัวที่ list ไว้
การรันตัวอย่าง
# Per-instrument Greeks
cargo run --example bybit-greeks-tester --package nautilus-bybit --features examples

# Option chain snapshots
cargo run --example bybit-option-chain --package nautilus-bybit --features examples
หยุดตัวอย่างใดก็ได้ด้วย Ctrl+C callback on_stop ของ actor
จะ unsubscribe ทุก stream ก่อนปิดระบบ
ผลลัพธ์ที่ตัวอย่างสร้างขึ้น
การรันบน mainnet 30 วินาทีในวันที่ 28 เมษายน (BTC ใกล้ 76,800 USDT, วันหมดอายุ 2026-04-28 08:00 UTC) ให้ผลดังนี้:
- tester ราย instrument จับ การอัปเดต Greeks ได้ 938 ครั้ง จากสัญญา BTC CALL 22 สัญญา
- tester ของ chain จับ snapshot ของ chain ได้ 5 ครั้ง แต่ละครั้งมี 7 strike
Output ของ Greeks ราย instrument
Found 22 BTC CALL options at nearest expiry (ts=1777359600000000000)
Subscribed to option greeks for 22 instruments
GREEKS | BTC-28APR26-72000-C-USDT-OPTION.BYBIT | delta=0.4733 gamma=0.000000 vega=0.0000 theta=-0.0000 rho=0.000000 | mark_iv=0.66 bid_iv=0.00 ask_iv=5.00 | underlying=76782.43 oi=0.0
GREEKS | BTC-28APR26-71000-C-USDT-OPTION.BYBIT | delta=0.4733 gamma=0.000000 vega=0.0000 theta=-0.0000 rho=0.000000 | mark_iv=0.74 bid_iv=0.00 ask_iv=5.00 | underlying=76782.43 oi=0.1
GREEKS | BTC-28APR26-73000-C-USDT-OPTION.BYBIT | delta=0.4733 gamma=0.000000 vega=0.0000 theta=-0.0000 rho=0.000000 | mark_iv=0.57 bid_iv=0.00 ask_iv=5.00 | underlying=76782.43 oi=0.0
Output ของ option chain
OPTION_CHAIN | BYBIT:BTC:USDT:2026-04-28T08:00:00Z | atm=77000 | calls=7 puts=7 | strikes=7
  K=75500 | CALL: bid=1210 ask=1430 [d=0.445 g=0.00000 v=0.00 iv=36.2%] | PUT: bid=0 ask=5 [d=0.000 g=0.00000 v=0.00 iv=36.2%]
  K=76000 | CALL: bid=700 ask=850 [d=0.445 g=0.00000 v=0.00 iv=32.5%] | PUT: bid=0 ask=5 [d=0.000 g=0.00000 v=0.00 iv=32.5%]
  K=76500 | CALL: bid=265 ask=370 [d=0.442 g=0.00000 v=0.07 iv=29.9%] | PUT: bid=0 ask=5 [d=-0.003 g=0.00000 v=0.07 iv=29.9%]
แผงภาพ
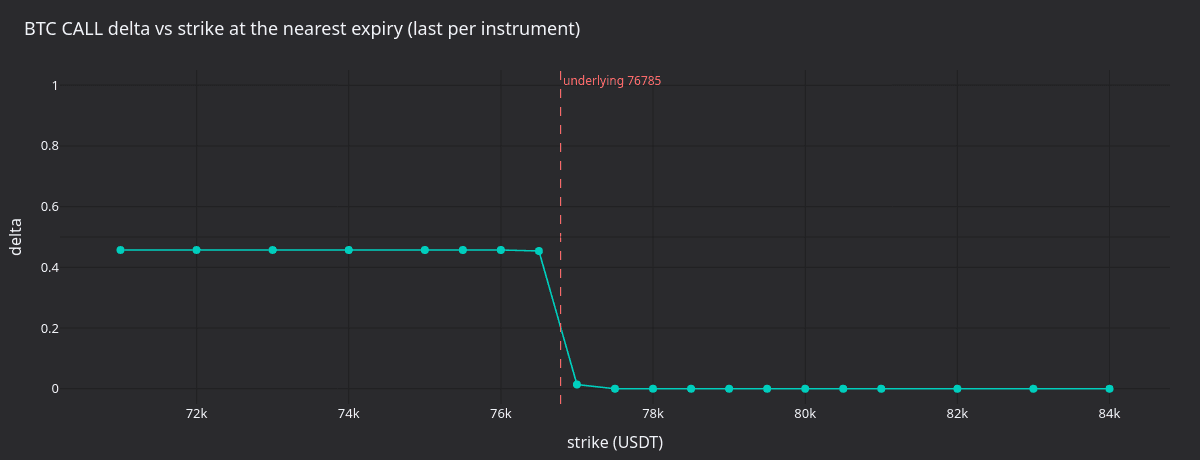
รูปที่ 1. delta ล่าสุดของแต่ละ strike ของ BTC CALL ที่วันหมดอายุใกล้ที่สุด โดยทำเครื่องหมาย underlying ที่ ~77,000 USDT ไว้ delta ลดลงจาก ~0.45 เมื่อต่ำกว่า underlying ไปจนเกือบเป็นศูนย์เมื่อเลย underlying ไป delta ของ Bybit บนสัญญาที่ gamma ใกล้ศูนย์และใกล้วันหมดอายุจะถูกบีบให้เป็นลักษณะขั้นบันไดรอบ ATM
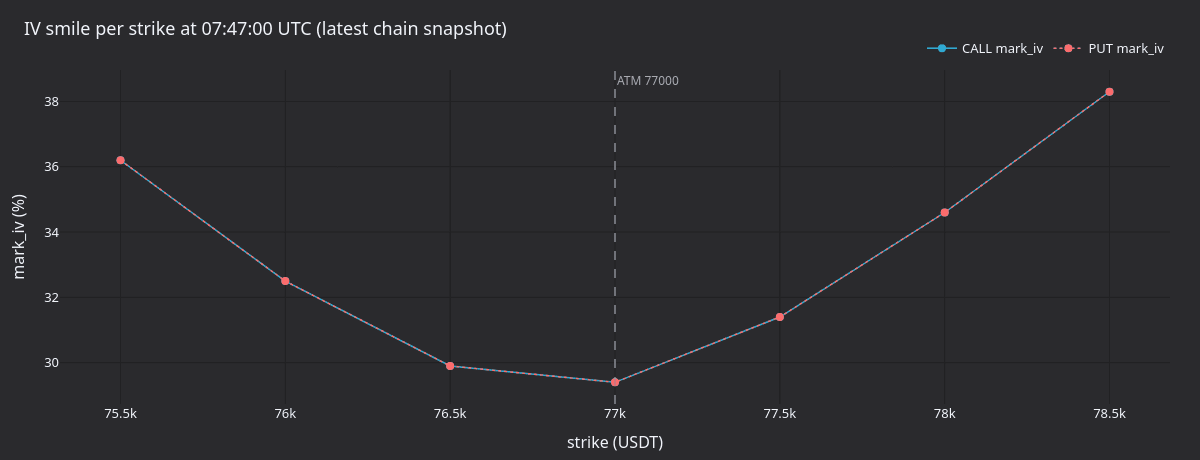
รูปที่ 2. Mark IV ของแต่ละ strike สำหรับ snapshot ของ chain ล่าสุด (CALL และ PUT ซ้อนกัน) smile สมมาตรรอบ ATM ที่ 77,000 USDT โดย IV ลดลงจาก 36% ที่ 75,500 เหลือ 30% ที่ 77,000 แล้วเพิ่มขึ้นเป็น 38% ที่ 78,500
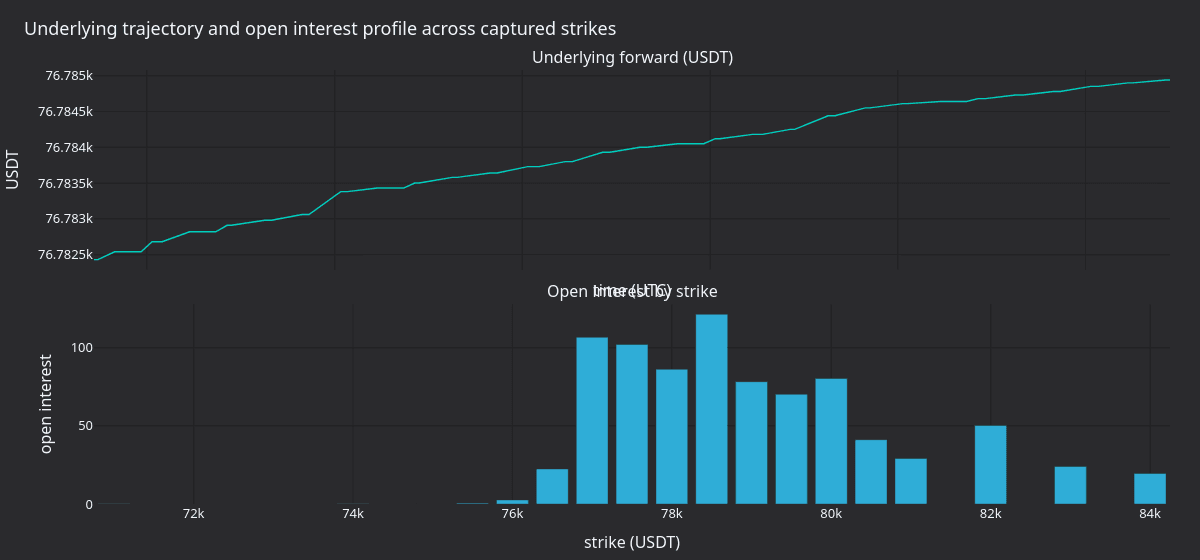
รูปที่ 3. ราคา underlying ของ Bybit ที่รายงานในการอัปเดต Greeks แต่ละครั้ง (บน) และ open interest ตาม strike ณ การอัปเดตล่าสุด (ล่าง) OI กระจุกตัวในช่วง [70,000, 76,000] USDT: strike ที่ at-the-money ไปจนถึง out-of-the-money เล็กน้อย
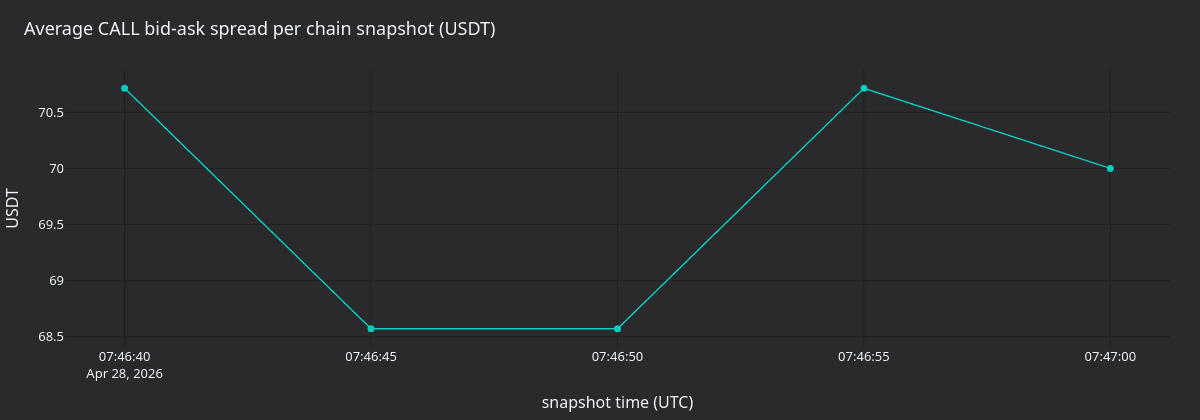
รูปที่ 4. bid-ask spread เฉลี่ยของ CALL ต่อ snapshot ของ chain หน่วยเป็น USDT
snapshot มาถึงทุกห้าวินาที (snapshot_interval_ms=5000)
การสร้างแผงภาพใหม่
หมายเหตุ: ต้นฉบับใช้สคริปต์ Python ในการ render แผงภาพ จึงตัดออก
Source code ฉบับเต็ม
ขั้นตอนถัดไป
- ผสมรูปแบบ: ใช้ Greeks ราย instrument สำหรับสัญญาที่ใกล้ ATM ควบคู่กับมุมมอง chain ที่รวมไว้แล้วใน actor เดียว subscribe Greeks สำหรับสัญญาที่ต้องการติดตามทีละตัว และ subscribe chain สำหรับมุมมองระดับ surface
- การ subscribe quote: เรียก
subscribe_quotesเพื่อรับการอัปเดตQuoteTickระดับ top-of-book ของสัญญา option แต่ละตัว - การ execute option:
tutorial strategy แบบ delta-neutral อธิบาย
short strangle พร้อมการ hedge ด้วย perpetual รวมถึงการวาง order แบบอิง IV
ผ่านพารามิเตอร์
order_ivของ Bybit
ดูเพิ่มเติม
- Options: ประเภทของ option instrument, data type ของ Greeks และสถาปัตยกรรมของ chain
- Bybit integration: ข้อมูลอ้างอิงฉบับเต็มของ adapter Bybit รวมถึงพารามิเตอร์ order ของ option และข้อจำกัด
แปลจาก เอกสาร NautilusTrader © Nautech Systems Pty Ltd และผู้ร่วมพัฒนา เผยแพร่ภายใต้ LGPL-3.0 ฉบับแปลนี้ตัดเนื้อหาเฉพาะ Python ออกและเน้น Rust